Editorial: France's fiscal mess has only one true solution
Published in Op Eds
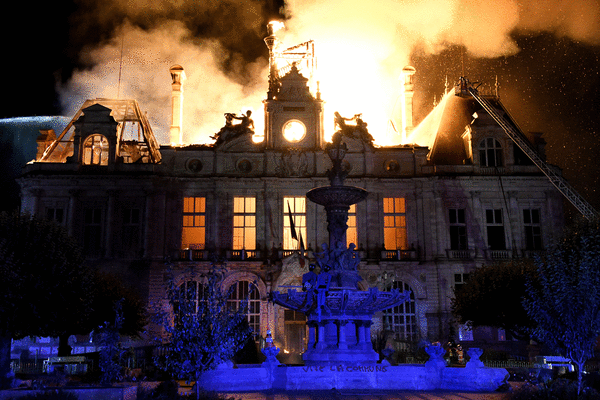
France’s crisis keeps getting more extreme, spilling over the weekend into broader protests that precipitated hundreds of millions of euros in damage and nearly 2,400 arrests. The country’s leaders are rightly focused on curtailing the violence. Yet as they seek ways to placate a frustrated populace, they must be careful not to make a bad fiscal situation worse.
It’s hard to overstate how dire France’s finances have become, particularly now that worried investors have pushed its 10-year bond yields to almost 5%. If borrowing costs remain this high, the interest rate the government pays will soon exceed the economy’s nominal growth rate. As a result, just stabilizing sovereign debt — currently about 120% of gross domestic product, among the highest in Europe — could require running a sustained primary budget surplus of as much as 2% of GDP. That’s a feat France hasn’t achieved since the 1970s.
The politics of achieving the necessary deficit reduction, estimated to be at least €125 billion by 2032, could hardly be more fraught. Among potential savings and revenue measures, pension reform stands out: Increasing the retirement age to 65 — still below the norm among western European peers — could reap about €18 billion. Yet when President Emmanuel Macron in 2023 pushed through an (ultimately postponed) increase from 62 to 64, the move triggered some of the country’s largest-ever protests — albeit rivaled in violence by the weekend’s events — and contributed to the far-right National Rally party’s success in 2024 elections.
With presidential elections coming next year, there’s even less appetite for prudence. The current minority government’s 2027 budget proposal, which would reduce the deficit by about €28 billion, faces stiff opposition. National Rally’s Marine Le Pen, who leads national polling for the next presidential election, sought to calm bond markets with a pledge of fiscal consolidation that contrasts sharply with the tax cuts and spending promises in her platform. Meanwhile, left-wing candidate Jean-Luc Mélenchon, whose statements have been blamed for inflaming protesters, proposed simply canceling more than €500 billion in French public debt held by its central bank — an absurdity that, even if possible, would serve only to spook markets more.
Eventually, the nation’s leaders will have to recognize that there’s no alternative to boring, unpleasant budget discipline. The longer that takes, the greater the damage will be.
France’s malaise places it on a collision course with the broader European Union. The longer it delays serious reform, the more precarious its finances will become as it takes on more debt at higher yields. If investors ultimately refuse to lend, the EU and the European Central Bank will face a dilemma: Organize a bailout or let the bloc’s second-largest economy descend into financial chaos. The best-case scenario would entail imposing austerity measures on France potentially harsher than what’s now needed to stabilize its debt. The worst would be an acute crisis involving a French default, bank runs and possibly a breakup of the euro.
If France’s current minority government can’t act, hopefully the next election will produce leadership capable of delivering the difficult reform the country needs. Even populists have been known to act responsibly when confronted with the immutable facts of public finance. There’s no better way out.
____
The Editorial Board publishes the views of the editors across a range of national and global affairs.
©2026 Bloomberg L.P. Visit bloomberg.com/opinion. Distributed by Tribune Content Agency, LLC.
Comments